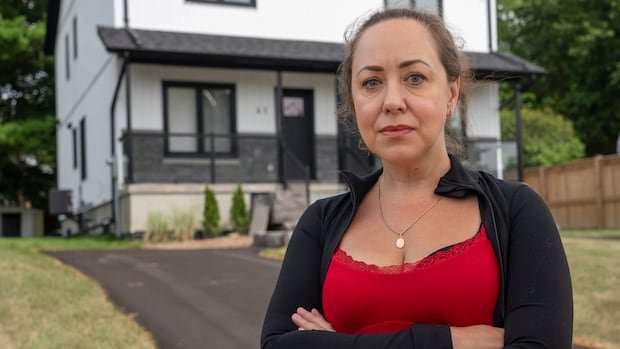
Antonina Gladkova faced challenges following a fire that ravaged her property in early 2024, leading to financial strain and frustration. Despite a smooth insurance process covering the house’s rebuild, her mortgage provider’s delayed release of funds created significant financial burdens. Gladkova’s warning to homeowners stems from her ordeal, emphasizing the importance of understanding mortgage agreements related to insurance claims.
The fire incident originated from a neighboring property, resulting in a total loss of Gladkova’s half of the semi-detached house in Georgetown, Ont. The insurance payout of over $508,000 for reconstruction was managed by the lender, Simplii Financial. However, Simplii’s partial fund release caused setbacks, prompting Gladkova to seek additional financing through a private mortgage due to the shortfall and construction delays.
Despite filing a complaint with Simplii, requesting further funds, the bank’s initial reluctance led to financial hardships for the couple. Eventually, Simplii adjusted its process to align funds with construction progress, but discrepancies persisted, resulting in delays and additional costs. Gladkova’s experience highlights the need for clear communication and alignment among property owners, lenders, contractors, and insurers to avoid similar financial pitfalls.
In response, Simplii expressed empathy for clients in property damage situations and emphasized the importance of understanding mortgage terms regarding insurance proceeds. Legal experts suggest establishing transparent communication among involved parties before construction commences to prevent funding discrepancies. Gladkova’s complaint with the Ombudsman for Banking Services and Investments (OBSI) sought compensation for incurred expenses, underscoring the need for improved mortgage agreements to streamline insurance payouts directly to contractors and alleviate financial burdens for homeowners.

