
For most Canadians, buying a property is the most significant financial transaction of their lives and a major investment. The decision between making a large down payment as a homeowner with higher monthly expenses or staying a renter and investing elsewhere is a crucial one. Which option ultimately leaves more money in your pocket?
Explore our simulator below for insights on how to use it effectively.
To address this dilemma, we delved into over two decades of historical data on property values, rents, inflation rates, interest rates in 22 Canadian cities, and long-term stock market performance.
Leveraging this data, we developed an interactive simulator. Each simulation calculates the monthly expenses and financial outcomes for three distinct scenarios: a homeowner with a fixed-rate mortgage, another with a variable-rate mortgage, and a renter. Any surplus from lower monthly costs as a renter is automatically invested in stocks and bonds for potential growth over time.
The simulator forecasts these financial scenarios over a 25-year period across 1,000 unique simulations. Some scenarios reflect high rents with low interest rates, while others simulate average inflation alongside modest stock market returns.
The calculations consider mortgage payments, insurance, property taxes, maintenance expenses, condo fees, rent, and future selling costs. Each outcome represents a plausible future based on historical trends and the chosen parameters.
However, it’s important to note that the future is unpredictable. This tool offers probabilities, not certainties, and should not be the sole basis for significant financial decisions. Below is a simplified version of our simulator. For a more in-depth version with additional choices and a detailed methodology breakdown, refer to the end of this article.
Shifts in Home Prices and Stock Performance
While our simulator provides valuable insights, it’s essential to recognize that past performance is not indicative of future outcomes. Macro-economic factors, such as demographic shifts, immigration patterns, market bubbles, and economic changes, constantly reshape the landscape.
Our tool is based on the last 25 years of data, excluding significant events like Canada’s housing crisis in the early 1990s. Experts caution that property maintenance costs can often exceed estimates, especially when unexpected repairs arise. Additionally, it’s uncommon for individuals to reside in the same property for a quarter-century.
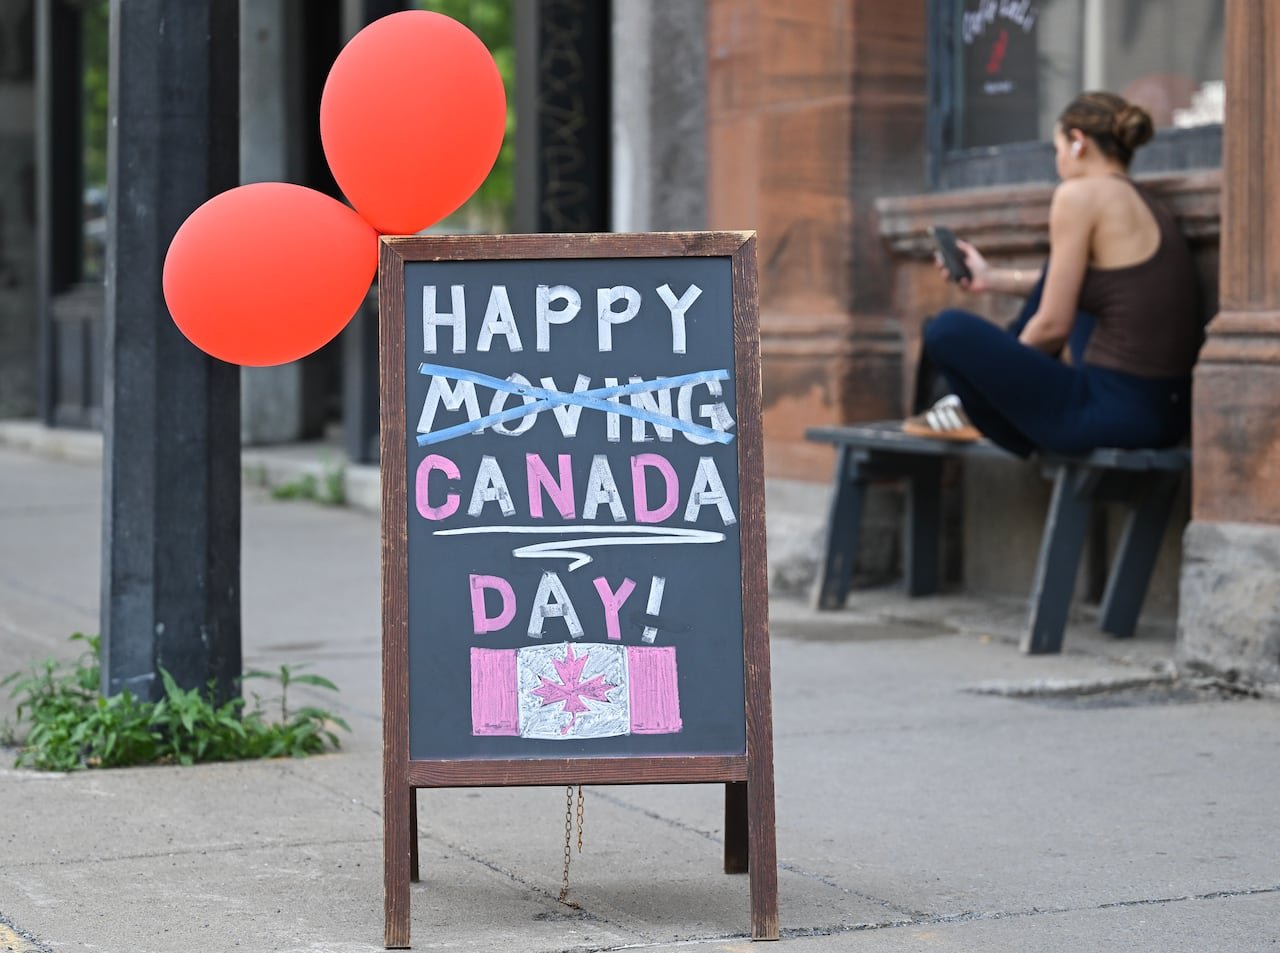
A sandwich board is shown on a street on Quebec’s unofficial moving day in Montreal on July 1. (Graham Hughes/The Canadian Press)
Recent trends indicate declining home prices, rising interest rates, increased property taxes, and maintenance expenses. Conversely, the stock market has demonstrated significant growth, with investments made in 2005 showing substantial returns compared to property investments from the same period.
Based on our analysis, renting an average studio or one-bedroom unit and diligently investing the saved funds can lead to favorable outcomes. However, upgrading to a larger space, like a two-bedroom apartment, can quickly alter the financial equation, as rising rent costs may erode potential savings and investment opportunities.
In many scenarios, renting eventually becomes more costly than owning. A homeowner’s primary expense is typically the mortgage payment, which, adjusted for inflation, diminishes over time.
- <li class="similarLink
